Rising Flood Insurance in Virginia Beach: FEMA Zones, Risk Rating 2.0, and Your Options
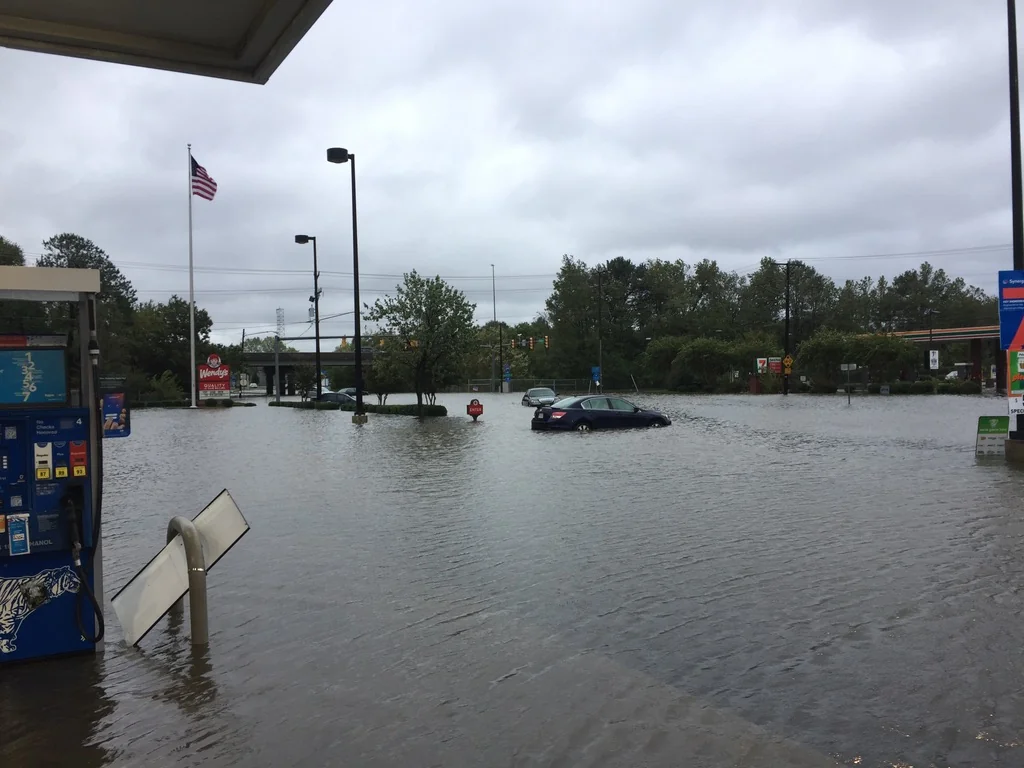
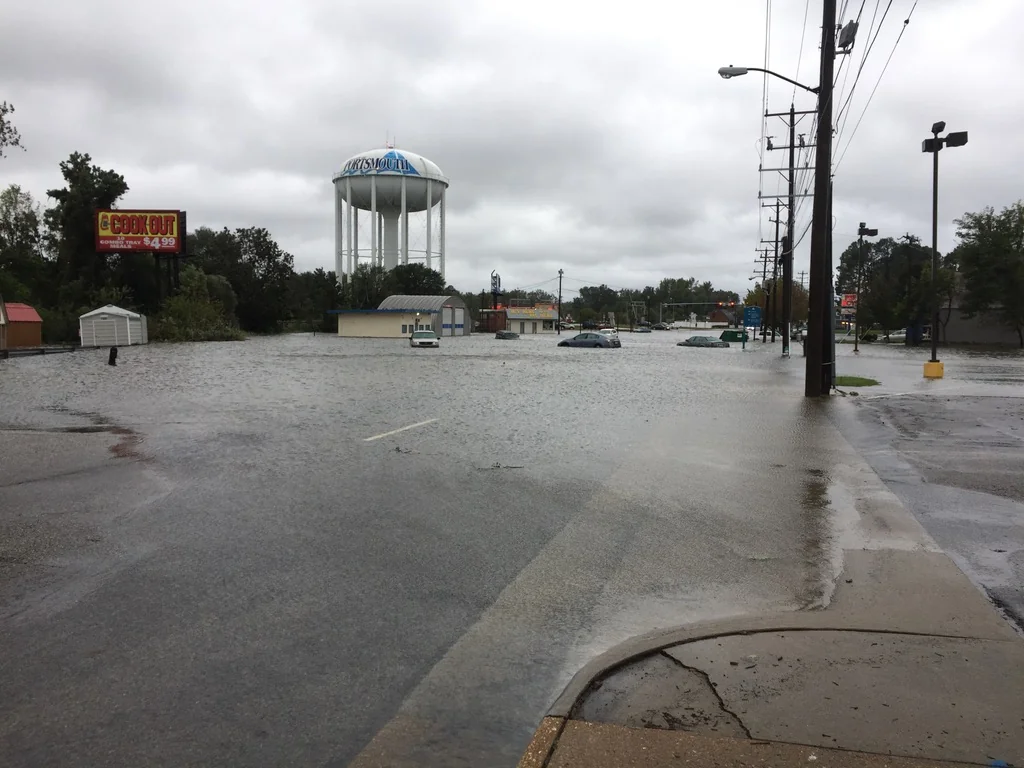
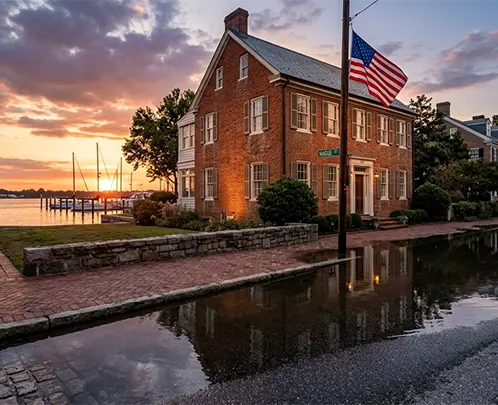
Virginia Beach has the longest coastline of any city in the Hampton Roads metro and the largest population at coastal flood risk. Whether your home sits in a designated AE zone two miles inland or a VE zone with direct ocean exposure, the FEMA Special Flood Hazard Area (SFHA) designation governs your federally-mandated flood insurance requirement, your NFIP Risk Rating 2.0 premium, and increasingly your resale options. This page walks through what each FEMA designation actually means, how Risk Rating 2.0 calculates your premium, and what the 2024 Hampton Roads flood-map update changed.
We're Hal and Emmy Jones; we have 17 years of experience buying homes, including in flood-zone neighborhoods.
Get Your Free Cash Offer Now!
Fill out this form to get your no-obligation all cash offer started!
Get Your Free Offer TODAY!
Fill In This Form To Get Your No-Obligation All Cash Offer Started!
Understanding FEMA Flood Zone Designations
FEMA publishes Flood Insurance Rate Maps (FIRMs) that designate every U.S. property's flood risk. The maps are available at the FEMA Flood Map Service Center. Common designations affecting Hampton Roads coastal property:
| Zone A | High-risk SFHA. 1% annual chance of flooding (the '100-year flood' zone). No detailed base flood elevation determined by FEMA studies. |
| Zone AE | High-risk SFHA. 1% annual chance of flooding with base flood elevation (BFE) determined and published on FIRMs. Most common Hampton Roads inland flood-zone designation. |
| Zone V | High-risk SFHA along coast. 1% annual chance of flooding with additional risk from wave action (3-foot wave heights or more). No detailed BFE. |
| Zone VE | High-risk SFHA along coast. 1% annual chance with detailed BFE and additional wave action. Most stringent insurance and building standards. Virginia Beach has extensive VE designation along the oceanfront. |
| Zone X (shaded) | Moderate-risk. 0.2%-1% annual chance (the '500-year flood' zone). Federally-backed mortgages do not require flood insurance, but insurance is recommended. |
| Zone X (unshaded) | Low-risk. Less than 0.2% annual chance. No flood insurance requirement. |
Properties in Zone A, AE, V, or VE with federally-backed mortgages are required by federal law to carry NFIP flood insurance. Lenders verify this at closing and typically require proof of continuing coverage annually. Letting NFIP coverage lapse can trigger lender force-placement at significantly higher rates.
The 2024 Hampton Roads Flood Map Update
FEMA periodically updates flood maps as new data becomes available. The 2024 update meaningfully expanded SFHA boundaries in parts of Hampton Roads. The expansion reflects:
- Improved coastal modeling incorporating updated storm surge data.
- Updated topographic data from LiDAR surveys.
- Incorporation of more recent flood event records.
- Adjustments for measured sea-level rise and subsidence in the region.
Some Virginia Beach (and other Hampton Roads) properties that were previously outside SFHA are now inside. If your property changed status in the 2024 update, your federally-backed mortgage now requires flood insurance even if it didn't before. Your insurance premium may have jumped accordingly. Check your specific property at the FEMA Flood Map Service Center.
NFIP Risk Rating 2.0 — How Your Premium Is Calculated
Effective April 1, 2023, FEMA fully implemented Risk Rating 2.0 — replacing the prior flood-zone-based pricing with individualized risk assessment. The new methodology evaluates each property on:
- Distance to water — Properties within 50 miles of the coast are evaluated against coastal flood risk including storm surge and coastal erosion. Distance to specific bodies of water is calculated; different bodies have different risk profiles.
- Elevation of the property relative to the flooding source. Higher-elevation properties pay less; lower-elevation properties pay more.
- Foundation type. Slab-on-grade vs raised foundation vs pilings affect risk and premium.
- First floor height. Higher first-floor elevation reduces premium.
- Full replacement cost. The cost to rebuild the home if total loss occurred. Higher-replacement-cost homes pay higher premiums.
- Specific local flood risks — inland flooding, storm surge, coastal erosion all evaluated separately.
Risk Rating 2.0 is actuarially sound. For some inland properties, premiums actually decreased under the new methodology. For many coastal Hampton Roads properties, premiums are climbing toward full risk-based rates over a multi-year transition.
The 18% / 25% Statutory Rate Caps
Congress capped annual NFIP rate increases under the Homeowner Flood Insurance Affordability Act (HFIAA) of 2014 (with subsequent amendments). Per FEMA Risk Rating 2.0 documentation:
- 18% per year maximum increase — primary residences
- 25% per year maximum increase — non-primary residences, non-residential properties, business properties, severe repetitive loss properties, properties with substantial cumulative damage, and properties with substantial damage or substantial improvement after July 6, 2012
The caps continue annually until the property reaches its full risk-based premium, which may take 10 to 15 years from the start of Risk Rating 2.0 transition. For coastal Virginia Beach properties with high inherent flood risk, this means premiums will climb materially every year for the foreseeable future.
The Community Rating System (CRS) Discount
Virginia Beach earns flood insurance discounts through the Community Rating System (CRS) — a FEMA program that rewards communities for floodplain management activities exceeding minimum NFIP requirements. CRS classes 1 through 9 (with 1 being best) produce discounts of 5% to 45% on NFIP premiums for properties within the community.
Virginia Beach recertifies its CRS participation annually, currently maintaining a discount around 15%. If the city's CRS class were downgraded, premiums would increase at the next renewal with no cap on that specific change. The CRS discount is a real reason that some Hampton Roads cities provide better insurance environments than others, and it's worth verifying your specific city's current CRS status before sale or refinance decisions.
When Does Cash Sale Through People First Make Sense?
If your Virginia Beach property's annual NFIP premium trajectory has crossed your tolerance line, or your property has changed status under the 2024 flood map update, or you've simply done the multi-year math against Risk Rating 2.0 and decided to exit — cash sale through People First is a structurally reliable path. We buy coastal Virginia Beach properties as-is, including those with active NFIP claims, recent flood damage, or VE-zone designation. No traditional inspection contingencies that fail on flood-related findings. No buyer financing fallout from changing insurability profiles. Closing in 7-14 days.
Frequently Asked Questions
What is FEMA Special Flood Hazard Area (SFHA)?
SFHA is the area with at least a 1% annual chance of flooding (the '100-year flood' zone). Includes Zone A, AE (inland) and Zone V, VE (coastal with wave action). Properties in SFHA with federally-backed mortgages are required by law to carry flood insurance.
How do I find my Virginia Beach property's flood zone?
Check the FEMA Flood Map Service Center at msc.fema.gov/portal/home. Enter your address; the map shows current FEMA designation. You can also order an Elevation Certificate from a licensed Virginia surveyor for detailed elevation data used in Risk Rating 2.0 premium calculations.
What is Risk Rating 2.0?
FEMA's new NFIP flood insurance pricing methodology, fully implemented April 1, 2023. Replaces flood-zone-based pricing with individualized risk assessment based on building characteristics, distance to water, elevation, foundation, and first floor height.
Why is my flood insurance premium going up every year?
Risk Rating 2.0 caps annual increases at 18% for primary residences and 25% for non-primary, business, severe repetitive loss, and substantially damaged properties. The caps continue annually until the property reaches its full risk-based rate — a 10-15 year transition for many properties.
Did the 2024 FEMA map update change my Virginia Beach property's flood zone?
Possibly. The 2024 update expanded SFHA boundaries in parts of Hampton Roads. If your property changed status, your federally-backed mortgage may now require flood insurance even if it didn't before. Check msc.fema.gov for your specific property.
Will People First buy my Virginia Beach home if flood insurance keeps going up?
Yes. We buy as-is, including Virginia Beach coastal properties with RL/SRL designation, recent flood damage, or insurability issues. Cash sale removes the inspection-and-financing contingencies that typically derail traditional buyer transactions on flood-affected properties.
Talk to Hal Directly
If your Virginia Beach home is in a flood zone and you want a straight read on your options, give us a call. We'll walk through your flood zone, your flood insurance costs, your timeline, and what a cash sale would look like — including whether it's even the right answer for your situation. People over profit. Honest feedback, even if we're not the best fit. Call (757) 238-5550 or fill out the form. — Hal and Emmy Jones, People First House Buyers.
Get Your Free Offer TODAY!
Fill In This Form To Get Your No-Obligation All Cash Offer Started!